Student Loan Repayment: New Federal Programs & Save 10% by June 2026
Anúncios
Student loan debt has long been a significant burden for millions of Americans, impacting everything from homeownership to retirement savings. The landscape of student loan repayment is constantly evolving, and staying informed about the latest federal programs is crucial for managing your debt effectively. With new initiatives and changes on the horizon, particularly the full implementation of the Saving on a Valuable Education (SAVE) Plan by July 2024, there’s a significant opportunity for borrowers to reduce their monthly payments. This comprehensive guide will delve into the new federal student loan repayment programs, with a special focus on how you can strategically leverage these changes to potentially save 10% or more on your monthly payments by June 2026.
Understanding the nuances of these programs can be complex, but the potential savings are substantial. Whether you’re a recent graduate, a seasoned professional, or someone who has been navigating student debt for years, this article will provide you with the knowledge and tools to make informed decisions and optimize your student loan repayment strategy.
Anúncios
The Evolving Landscape of Student Loan Repayment: Why Now is Critical
The past few years have seen unprecedented shifts in federal student loan policy. From the pandemic-era payment pause to the introduction of new income-driven repayment (IDR) plans, borrowers have had to adapt to a dynamic environment. The most significant recent development is the rollout of the SAVE Plan, which promises to be the most affordable IDR plan ever offered. Its full benefits will become available in July 2024, making the period leading up to June 2026 a critical window for borrowers to understand and enroll in this program.
Many borrowers are still grappling with the restart of payments after the pause, and the financial strain can be considerable. However, these new programs are designed to provide much-needed relief, making student loan repayment more manageable and preventing defaults. Ignoring these changes could mean missing out on significant savings and opportunities for loan forgiveness.
Anúncios
Introducing the SAVE Plan: A Game Changer for Student Loan Repayment
What is the SAVE Plan?
The Saving on a Valuable Education (SAVE) Plan is a new income-driven repayment (IDR) plan that replaces the Revised Pay As You Earn (REPAYE) Plan. It’s designed to significantly lower monthly payments for many borrowers by recalculating payments based on a larger portion of their discretionary income. The core idea behind IDR plans is to make monthly student loan payments affordable by capping them at a percentage of your discretionary income, and the SAVE Plan takes this concept further than ever before.
Key Benefits of the SAVE Plan
The SAVE Plan offers several key advantages that set it apart from previous IDR plans:
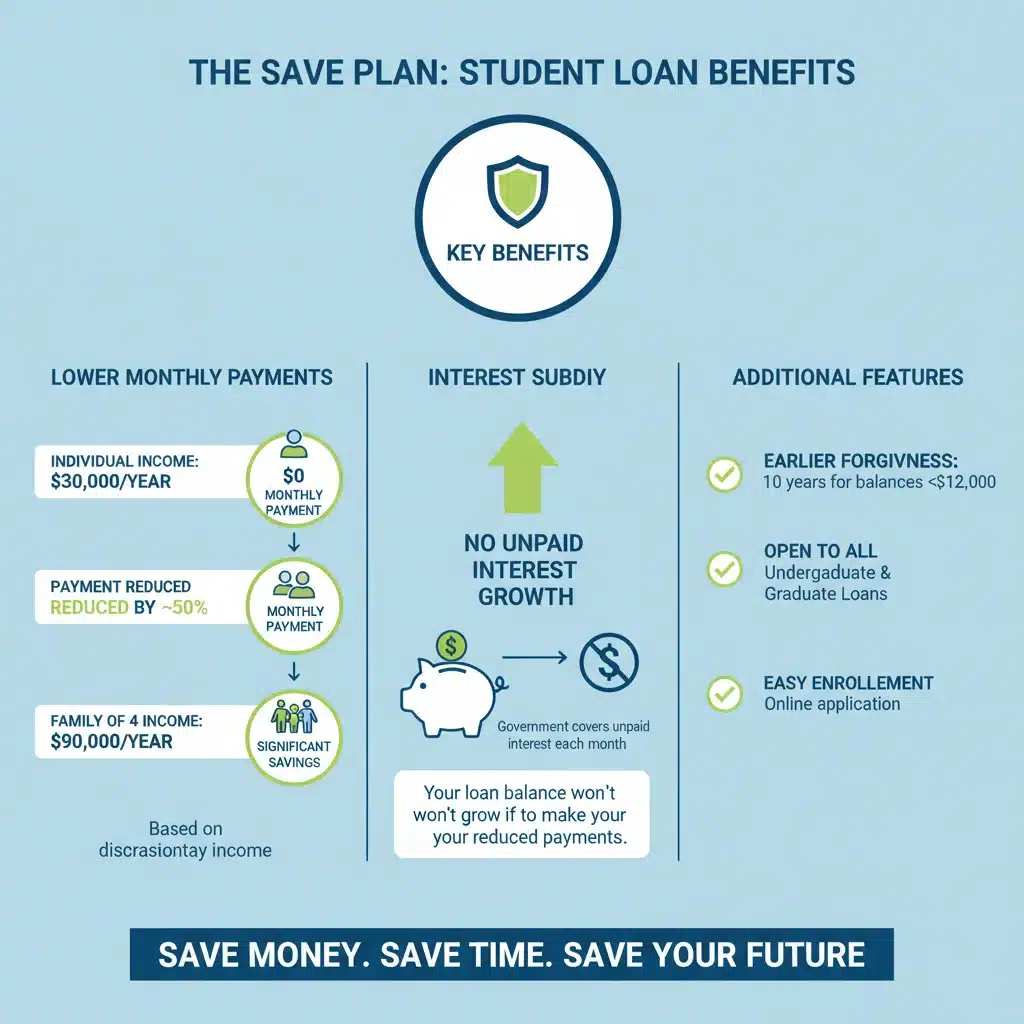
- Lower Monthly Payments: For undergraduate loans, monthly payments will be cut from 10% to 5% of discretionary income. This change will be fully implemented by July 2024. Borrowers with both undergraduate and graduate loans will pay a weighted average between 5% and 10%.
- Increased Discretionary Income Exemption: The amount of income protected from payment calculations has increased from 150% to 225% of the federal poverty line. This means more of your income is considered non-discretionary, leading to lower calculated payments. For a single borrower, this could mean an additional $1,500 in protected income annually compared to other IDR plans.
- No Unpaid Interest Accumulation: This is arguably one of the most significant benefits. If your calculated monthly payment doesn’t cover the interest that accrues each month, the government will cover the remaining interest. This prevents your loan balance from growing, even if your payments are $0. This feature went into effect in summer 2023.
- Faster Path to Forgiveness: Borrowers with original loan balances of $12,000 or less can receive forgiveness after as few as 10 years of payments. For every additional $1,000 borrowed above $12,000, an additional year of payments is required, up to a maximum of 20 or 25 years.
- Spousal Income Exclusion: If you are married and file taxes separately, your spouse’s income will not be included in the calculation of your monthly payment. This can significantly reduce payments for many married borrowers.
Who is Eligible for the SAVE Plan?
Most federal student loan borrowers with Direct Loans are eligible for the SAVE Plan. This includes:
- Direct Subsidized Loans
- Direct Unsubsidized Loans
- Direct PLUS Loans made to students
- Direct Consolidation Loans (that did not include Parent PLUS loans)
Federal Family Education Loan (FFEL) Program loans and Perkins Loans are generally not eligible unless they are consolidated into a Direct Consolidation Loan. Parent PLUS loans are not eligible for the SAVE Plan directly, but they can be included in a Direct Consolidation Loan, which can then be repaid under the Income-Contingent Repayment (ICR) Plan. However, to access the SAVE Plan’s benefits for Parent PLUS loans, a double consolidation strategy might be necessary, which is complex and worth discussing with a financial aid expert.
How to Save 10% (or More) on Your Monthly Payments by June 2026
The goal is clear: reduce your student loan repayment burden. Here’s a strategic roadmap to achieve significant savings by June 2026, leveraging the SAVE Plan and other available resources.
Step 1: Understand Your Current Loan Portfolio
Before you can optimize, you need to know what you’re working with. Log in to your Federal Student Aid (FSA) account at studentaid.gov. Here you can see:
- Loan types: Direct Loans, FFEL, Perkins, Parent PLUS.
- Loan servicers: Who manages your loans.
- Current balances and interest rates: Crucial for understanding your total debt.
- Current repayment plan: Are you on a Standard, Graduated, or another IDR plan?
This information is foundational to determining your eligibility for various programs and selecting the best path forward.
Step 2: Consolidate Loans if Necessary
If you have FFEL or Perkins Loans, consolidating them into a Direct Consolidation Loan is often a prerequisite for enrolling in the SAVE Plan and other IDR plans. Consolidation combines multiple federal loans into a single new loan with a single interest rate (a weighted average of the old rates). While it doesn’t always lower your interest rate, it can open doors to more flexible repayment options and potential forgiveness programs.
Important Note: If you have Parent PLUS loans, and you want to access the SAVE Plan, you might need to explore a ‘double consolidation’ strategy. This involves consolidating the Parent PLUS loans into an initial Direct Consolidation Loan, and then consolidating that new loan with at least one other Direct Loan (or another Direct Consolidation Loan) into a second Direct Consolidation Loan. This complex process effectively changes the loan type, making it eligible for the SAVE Plan. Due to its complexity, it’s highly recommended to consult with a student loan expert or the Department of Education before attempting double consolidation.
Step 3: Apply for the SAVE Plan
This is the most direct route to reducing your monthly payments. You can apply for the SAVE Plan (or switch from another IDR plan to SAVE) through StudentAid.gov/IDR. You’ll need to provide information about your income and family size. The application process is generally straightforward and can often be completed online.
What to Expect:
- Immediate Benefits: Some benefits of the SAVE Plan, like the interest subsidy, are already in effect.
- Full Implementation by July 2024: The reduction of undergraduate loan payments to 5% of discretionary income will be fully implemented by July 2024. Enrolling now ensures you’re ready to receive these maximum benefits as soon as they become available.
- Annual Recertification: Like all IDR plans, you’ll need to recertify your income and family size annually. Mark your calendar for this, as failing to recertify can lead to higher payments and capitalized interest.
Step 4: Explore Other Federal Programs and Strategies
While the SAVE Plan is a powerful tool, it’s not the only option. Consider these additional strategies:
Public Service Loan Forgiveness (PSLF)
If you work for a U.S. federal, state, local, or tribal government or a non-profit organization, you might be eligible for PSLF. This program forgives the remaining balance on your Direct Loans after you’ve made 120 qualifying monthly payments (10 years) under a qualifying repayment plan (like the SAVE Plan) while working full-time for a qualifying employer. The SAVE Plan is an excellent choice for PSLF-eligible borrowers because it often leads to the lowest monthly payments, maximizing the amount forgiven.
Teacher Loan Forgiveness
For teachers who work for five complete and consecutive academic years in a low-income school or educational service agency, up to $17,500 in loan forgiveness may be available for certain Direct Subsidized and Unsubsidized Loans and FFEL Program loans.
Income-Contingent Repayment (ICR) Plan
While often less generous than the SAVE Plan, ICR is notably the only IDR plan available for Direct Consolidation Loans that include Parent PLUS loans (without the double consolidation strategy). Payments are capped at 20% of discretionary income or what you’d pay on a fixed 12-year payment plan, whichever is less.
Deferment and Forbearance
These options allow you to temporarily postpone or reduce your payments. While they can provide short-term relief, interest often continues to accrue, potentially increasing your total loan cost. They should generally be used as a last resort, or during periods of significant financial hardship.
Perkins Loan Cancellation
If you have Perkins Loans, certain professions (e.g., teaching in low-income schools, nursing, law enforcement) may qualify you for partial or full loan cancellation.
Step 5: Optimize Your Income and Family Size Reporting
Your monthly payment under the SAVE Plan (and other IDR plans) is directly tied to your discretionary income and family size. Therefore, strategically managing these factors can lead to lower payments:
- File Taxes Separately (if married): As mentioned, under the SAVE Plan, if you file federal income taxes separately from your spouse, their income will not be included in your payment calculation. This can result in significantly lower payments for many married borrowers, though it’s important to consider the overall tax implications of filing separately.
- Update Family Size: If your family size increases (e.g., birth or adoption of a child), update this information with your loan servicer promptly. A larger family size increases your protected income, which can lower your monthly payment.
- Report Income Changes: If your income decreases significantly, don’t wait for your annual recertification. You can request a recalculation of your payment based on your new, lower income at any time.
Step 6: Plan for Annual Recertification
To remain on an IDR plan, you must recertify your income and family size annually. Your loan servicer will notify you when it’s time to recertify. Missing this deadline can have serious consequences, including your payments reverting to the standard plan (which will likely be much higher) and any unpaid interest capitalizing (being added to your principal balance).
Tips for Recertification:
- Set Reminders: Use calendar reminders, phone alerts, or recurring tasks to ensure you don’t miss your recertification deadline.
- Use the IRS Data Retrieval Tool: When available, this tool on StudentAid.gov allows you to securely transfer your tax information directly from the IRS, simplifying the process and reducing errors.
- Keep Records: Maintain copies of all documents submitted and confirmations received from your loan servicer.
The Importance of Acting Now: Why June 2026 is a Key Target
The full benefits of the SAVE Plan, particularly the reduction to 5% of discretionary income for undergraduate loans, will be implemented in July 2024. This means that by enrolling now or in the coming months, you position yourself to take full advantage of these lower payments. The period leading up to June 2026 allows you to make consistent, lower payments, prevent interest from capitalizing, and make significant progress towards potential loan forgiveness.
Furthermore, the no-interest accumulation benefit is a game-changer. For many borrowers, even those making $0 payments, their loan balance will no longer grow due to unpaid interest. This removes a major psychological and financial barrier to student loan repayment, making the prospect of eventually paying off the debt much more realistic.
Delaying action could mean missing out on months of reduced payments and the significant interest subsidy. Every month you pay more than you need to, or allow interest to accrue unnecessarily, is a lost opportunity for financial relief.
Common Pitfalls to Avoid in Student Loan Repayment
Navigating student loan repayment can be tricky. Here are some common mistakes to avoid:
- Ignoring Your Loans: Burying your head in the sand is the worst strategy. Unpaid loans can lead to default, damaged credit, wage garnishment, and tax refund offsets.
- Not Knowing Your Loan Types: Different loan types have different eligibility for repayment plans and forgiveness programs. Understand what you have.
- Missing Recertification Deadlines: As discussed, this can lead to payment spikes and capitalized interest.
- Falling for Scams: Be wary of companies promising quick fixes or guaranteed forgiveness for a fee. Most federal loan services are free. Always go through StudentAid.gov or your official loan servicer.
- Not Considering Consolidation: For some, consolidation is essential to access better repayment plans. Understand if it’s right for you.
- Overpaying on IDR Plans: While extra payments can be good, if you’re on an IDR plan and aiming for forgiveness, overpaying might not be the most efficient strategy, especially if your payments are already low and the government is subsidizing interest. Focus on maximizing forgiveness if that’s your goal.
Beyond Federal Programs: Additional Financial Strategies
While federal programs are the cornerstone of smart student loan management, integrating them with broader financial planning can amplify your savings and accelerate your financial goals:
- Budgeting: Create a detailed budget to understand your income and expenses. This helps identify areas where you can cut back to free up funds, potentially for extra loan payments (if not on a forgiveness track) or other financial goals.
- Emergency Fund: Build an emergency fund of 3-6 months of living expenses. This safety net prevents you from falling behind on loan payments if unexpected expenses arise.
- Debt Snowball/Avalanche: If you have other debts (credit cards, personal loans) in addition to student loans, consider the debt snowball (paying smallest balance first) or debt avalanche (paying highest interest first) methods to tackle them. This can free up more cash flow for your student loans.
- Refinancing (Private Loans Only): If you have private student loans (which are not eligible for federal programs), you might consider refinancing them with a private lender to get a lower interest rate. Be cautious: refinancing federal loans into private loans means losing access to all federal benefits, including IDR plans and forgiveness.
- Increase Income: Explore ways to boost your income, such as a side hustle, negotiating a raise, or seeking a higher-paying job. More income can provide more flexibility in your budget.
Conclusion: Take Control of Your Student Loan Repayment Journey
The new federal student loan repayment programs, particularly the SAVE Plan, represent a significant opportunity for millions of borrowers to alleviate financial stress and achieve greater financial stability. By understanding your loan portfolio, consolidating if necessary, and strategically enrolling in the SAVE Plan, you can realistically aim to reduce your monthly student loan repayment by 10% or more by June 2026. This isn’t just about saving money; it’s about gaining control over your financial future, freeing up resources for other life goals, and preventing the long-term burden of escalating debt.
Don’t wait. The time to act is now. Visit StudentAid.gov, gather your information, and explore how these programs can work for you. Proactive engagement with your student loans is the most effective way to navigate the repayment landscape and secure your financial well-being. Remember, help is available, and understanding your options is the first crucial step towards a more manageable and sustainable student loan repayment journey.