Medicare Part B 2026: Understanding the 2.5% Premium Adjustment
Anúncios
In the dynamic landscape of healthcare, understanding the nuances of Medicare, particularly its premium adjustments, is paramount for current and future beneficiaries. As we look ahead to 2026, a projected 2.5% adjustment to Medicare Part B premiums is on the horizon. This adjustment, while seemingly small, carries significant implications for millions of Americans who rely on Medicare for their medical insurance needs. This comprehensive guide aims to dissect the factors influencing this change, explore its potential impact on beneficiaries, and offer strategies for navigating these evolving healthcare costs.
Anúncios
Understanding Medicare Part B: A Foundation
Before diving into the specifics of the 2026 adjustment, it’s crucial to have a clear understanding of what Medicare Part B entails. Medicare Part B, often referred to as medical insurance, covers medically necessary services like doctors’ visits, outpatient care, preventive services, and some medical equipment. Unlike Part A (hospital insurance), which is typically premium-free for most beneficiaries, Part B requires a monthly premium. This premium can vary based on income, a concept known as the Income-Related Monthly Adjustment Amount (IRMAA).
The costs associated with Medicare Part B are not static. They are subject to annual adjustments, influenced by a complex interplay of economic factors, healthcare utilization trends, and legislative decisions. These adjustments are critical because they directly affect the out-of-pocket expenses for beneficiaries, impacting their overall financial planning for retirement and healthcare.
Anúncios
The Projected 2.5% Adjustment for Medicare Part B 2026: What It Means
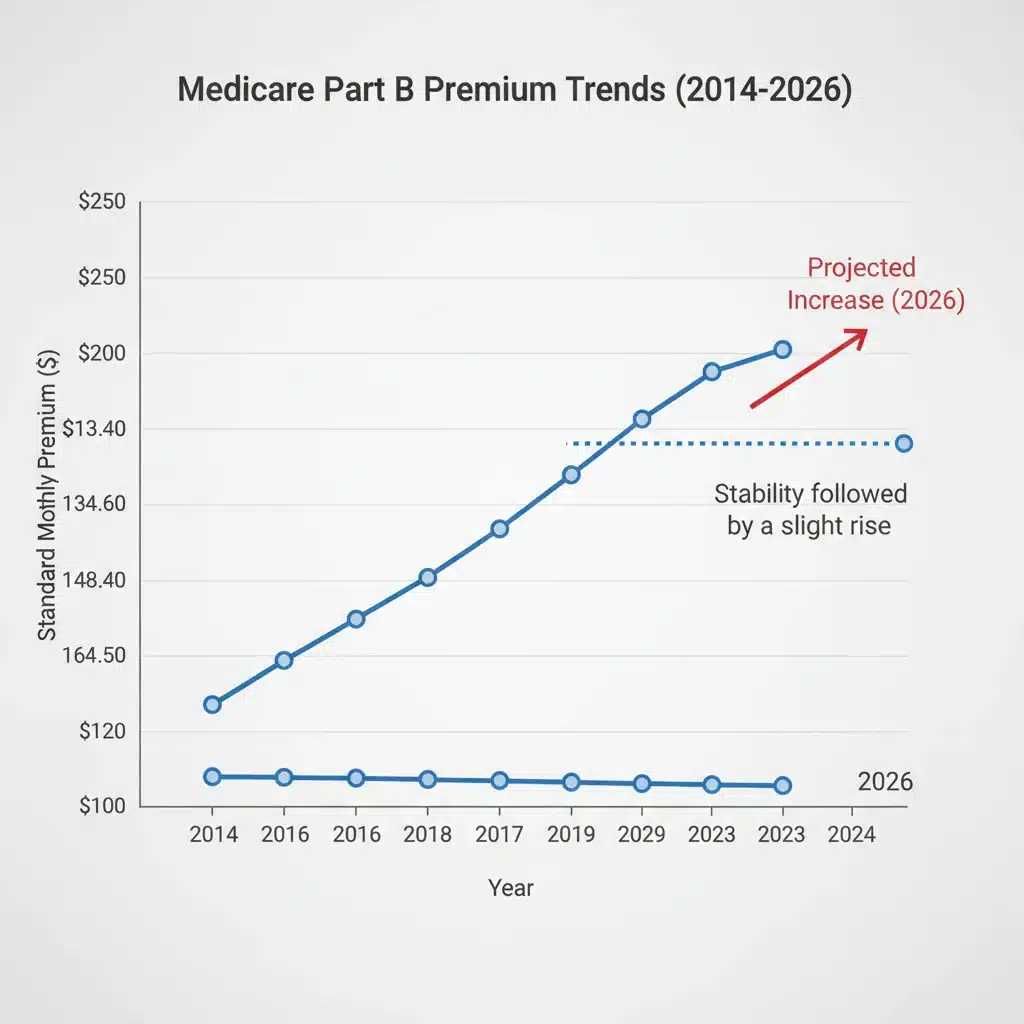
The anticipation of a 2.5% increase in Medicare Part B premiums for 2026 is a key point of discussion for many. This figure represents a projection based on current trends and actuarial estimates. While the exact percentage is subject to final determination by the Centers for Medicare & Medicaid Services (CMS) later, such projections offer valuable foresight for planning purposes.
A 2.5% increase means that if the standard Part B premium were, for example, $174.70 in 2025, it would rise to approximately $179.08 in 2026. While this might seem like a modest bump on a monthly basis, it accumulates over the year and can have a more substantial impact on those with higher incomes who are already paying higher IRMAA surcharges. For many seniors on fixed incomes, even small increases can necessitate adjustments to their budgets and financial strategies.
It’s important to remember that this 2.5% is an average. Individual premium amounts can still vary significantly based on income, as explained by the IRMAA framework. Therefore, understanding the broader implications of this adjustment requires a deeper look into the factors driving it and how it interacts with individual financial circumstances.
Key Factors Driving the Medicare Part B 2026 Premium Adjustment
Several critical factors contribute to the annual adjustments in Medicare Part B premiums. Understanding these drivers provides insight into why a 2.5% increase for Medicare Part B 2026 is projected:
- Healthcare Spending Trends: The overall cost of healthcare services in the U.S. is a primary determinant. Increases in the cost of medical procedures, prescription drugs, doctor’s fees, and hospital outpatient services directly impact Medicare’s expenditures.
- Utilization of Services: How frequently beneficiaries use Part B services also plays a role. Higher utilization rates, driven by factors such as an aging population or increased prevalence of chronic conditions, can lead to higher program costs.
- Inflation: General economic inflation affects all sectors, including healthcare. The rising cost of labor, supplies, and administrative overhead for healthcare providers contributes to increased expenditures for Medicare.
- Prescription Drug Costs: While many prescription drugs are covered under Medicare Part D, some drugs administered in a doctor’s office or outpatient setting fall under Part B. The escalating costs of these drugs can exert upward pressure on premiums.
- Legislative Changes and Policy Decisions: New healthcare policies, legislative mandates, or changes in how Medicare is funded can also influence premium adjustments. These can include initiatives to improve healthcare quality, expand coverage, or manage costs.
- The ‘Hold Harmless’ Provision: This provision generally prevents most beneficiaries from seeing their Part B premium increase by more than the dollar amount of their Social Security cost-of-living adjustment (COLA). However, it doesn’t apply to everyone, especially those new to Medicare, those who don’t receive Social Security benefits, or those paying IRMAA. The interplay between COLA and premium increases is complex and can influence the overall average adjustment.
- Medicare Trust Fund Balances: The financial health of the Supplementary Medical Insurance (SMI) Trust Fund, which funds Part B, is regularly assessed. Actuaries project future expenditures and revenues, and these projections inform premium adjustments to ensure the program’s solvency.
The 2.5% projection for Medicare Part B 2026 is a result of these factors being weighed and calculated by CMS and the Medicare actuaries. It’s an attempt to balance the need to fund the program’s services with the desire to keep costs manageable for beneficiaries.
Impact on Beneficiaries: Who Will Be Affected by the Medicare Part B 2026 Adjustment?
While a 2.5% increase might seem uniform, its impact will vary significantly among different groups of Medicare beneficiaries. Understanding these varying effects is crucial for personalized financial planning:
Those Protected by the Hold Harmless Provision
The ‘hold harmless’ provision is a critical safeguard for many. It dictates that most beneficiaries’ Part B premium increase cannot exceed the increase in their Social Security benefit payments. This means that if your Social Security COLA for 2026 is, for example, $5.00, your Part B premium cannot increase by more than $5.00, even if the standard premium increase is higher. This provision primarily protects those who have their Part B premiums deducted directly from their Social Security checks.
However, it’s important to note that the hold harmless provision does not apply to:
- New Medicare beneficiaries.
- Beneficiaries who do not receive Social Security benefits.
- Beneficiaries whose modified adjusted gross income (MAGI) exceeds certain thresholds, making them subject to IRMAA.
- Beneficiaries who pay their Part B premiums directly (e.g., through direct bill or bank draft).
Beneficiaries Subject to IRMAA
The Income-Related Monthly Adjustment Amount (IRMAA) means that higher-income beneficiaries pay a higher Part B premium. For Medicare Part B 2026, the IRMAA thresholds will also be adjusted, potentially leading to a compound effect for these individuals. A 2.5% increase on an already higher premium means a larger dollar amount increase. For example, if someone is in an IRMAA bracket that doubles their standard premium, a 2.5% increase on that doubled amount will be more significant than on the standard premium.
IRMAA is based on your MAGI from two years prior. So, for 2026 premiums, your 2024 income will be used. This lag can be a surprise for some, especially if their income has significantly decreased in the intervening years.
New Medicare Beneficiaries and Those Not Receiving Social Security
Individuals who are new to Medicare in 2026 or those who do not have their Part B premiums deducted from Social Security will likely face the full brunt of the 2.5% increase. They will pay the standard premium (or higher, if subject to IRMAA) without the protection of the hold harmless provision. This highlights the importance of understanding the premium structure when initially enrolling in Medicare.
Strategies for Managing Medicare Part B 2026 Costs
Given the projected 2.5% adjustment for Medicare Part B 2026, proactive planning is essential. Here are several strategies beneficiaries can employ to manage their healthcare costs:
1. Understand Your Income and IRMAA
Since IRMAA is based on your income from two years prior, it’s crucial to review your tax returns from 2024 (for 2026 premiums). If you’ve had a significant life event that reduced your income (e.g., retirement, divorce, death of a spouse, work stoppage), you may be able to appeal your IRMAA determination to Social Security. This could potentially lower your Part B premiums.
2. Maximize Preventive Services
Medicare Part B covers a wide range of preventive services, often at no additional cost. Utilizing these services, such as annual wellness visits, screenings, and vaccinations, can help detect health issues early, potentially preventing more serious and costly conditions down the line. Staying healthy is one of the best ways to control healthcare expenses.
3. Explore Medicare Advantage (Part C) Plans
Medicare Advantage plans are offered by private companies approved by Medicare. Many of these plans include Part B coverage and may offer additional benefits like prescription drug coverage, vision, dental, and hearing. Some Medicare Advantage plans even have $0 monthly premiums (beyond your Part B premium). It’s worth exploring these options to see if a Medicare Advantage plan could provide more comprehensive coverage or lower overall out-of-pocket costs, depending on your health needs and preferences.
4. Consider Medigap (Medicare Supplement) Plans
Medigap policies help cover some of the out-of-pocket costs that original Medicare (Parts A and B) doesn’t, such as deductibles, copayments, and coinsurance. While Medigap plans have their own premiums, they can provide predictable costs and reduce the financial burden of unexpected medical expenses. If you frequently use Part B services, a Medigap plan could offer significant savings, even with the 2.5% increase in your Part B premium.
5. Review Your Prescription Drug Coverage (Part D)
While Part B covers some drugs, most prescription drugs are covered under Part D. It’s vital to review your Part D plan annually during the Open Enrollment Period to ensure it still meets your needs and offers the most cost-effective coverage for your medications. High drug costs can significantly impact your overall healthcare budget.
6. Utilize State and Federal Assistance Programs
Several programs can help low-income beneficiaries with their Medicare costs, including the Medicare Savings Programs (MSPs). These programs can help pay for Part B premiums, deductibles, and copayments. There are different levels of MSPs, and eligibility depends on income and asset limits. It’s worth investigating if you qualify for any of these vital assistance programs.
7. Budgeting and Financial Planning
Integrate the projected 2.5% increase for Medicare Part B 2026 into your long-term financial planning. Account for healthcare costs as a significant part of your retirement budget. Regular review and adjustment of your budget will help you stay ahead of these changes.
The Broader Economic and Healthcare Context
The 2.5% adjustment for Medicare Part B 2026 doesn’t occur in a vacuum. It’s part of a larger narrative concerning healthcare costs, an aging population, and the sustainability of federal programs. The U.S. healthcare system continues to grapple with rising expenditures, driven by technological advancements, increased demand, and the complexities of chronic disease management.
As the baby boomer generation continues to age into Medicare eligibility, the number of beneficiaries is steadily increasing. This demographic shift places greater demands on the Medicare system, necessitating careful financial management and periodic adjustments to premiums and deductibles. Policymakers are constantly seeking ways to balance providing comprehensive care with controlling costs, and premium adjustments are one mechanism for achieving this balance.
Furthermore, discussions around potential legislative changes to Medicare are ongoing. These could involve reforms to drug pricing, adjustments to benefit structures, or changes to how the program is funded. While the 2.5% projection for 2026 is based on current law and trends, future legislative actions could introduce new variables into the equation. Staying informed about these broader policy discussions can help beneficiaries anticipate future changes.
The Role of the Medicare Trustees’ Report
Each year, the Medicare Board of Trustees releases a comprehensive report detailing the financial status of the Medicare Trust Funds. This report provides critical insights into the program’s short-term and long-term financial outlook, including projections for expenditures, revenues, and the solvency of the trust funds. The projections for Medicare Part B 2026 premiums are heavily influenced by the findings and recommendations within this report.
The Trustees’ Report analyzes various economic and demographic assumptions, such as inflation rates, wage growth, healthcare spending trends, and population demographics. Based on these analyses, they project the necessary adjustments to premiums and deductibles to ensure the program can continue to meet its obligations to beneficiaries. Therefore, the 2.5% projected increase for Part B in 2026 is not an arbitrary figure but a carefully calculated estimate rooted in extensive actuarial analysis.
Beneficiaries and stakeholders often scrutinize this report to understand the underlying rationale for premium adjustments and to assess the overall health of the Medicare program. It serves as a vital tool for transparency and accountability in Medicare’s financial management.
Preparing for Future Adjustments
The 2.5% adjustment for Medicare Part B 2026 is a reminder that healthcare costs are not static. Beneficiaries should prepare for ongoing adjustments to premiums, deductibles, and copayments in the years to come. Here are some forward-looking preparation tips:
- Stay Informed: Regularly check official Medicare resources (Medicare.gov, CMS.gov) for the latest updates on premiums, deductibles, and coverage changes.
- Annual Review: Make it a habit to review your entire Medicare coverage (Parts A, B, D, and any supplemental plans) annually during the Open Enrollment Period (October 15 – December 7). This is your opportunity to switch plans, adjust coverage, and ensure you have the most cost-effective options for your health needs.
- Consult a Financial Advisor: A financial advisor specializing in retirement planning can help you integrate Medicare costs into your overall financial strategy, particularly concerning IRMAA and long-term healthcare expenses.
- Maintain Good Health: While not a direct financial strategy, maintaining a healthy lifestyle can reduce the need for extensive medical interventions, thereby potentially lowering out-of-pocket costs in the long run.
- Understand Your Benefits: Fully grasp what Medicare Part B covers and what it doesn’t. This knowledge helps you avoid unexpected costs and make informed decisions about supplemental coverage.
Conclusion
The projected 2.5% adjustment for Medicare Part B 2026 premiums is a crucial development for millions of Americans. While it’s an estimated figure, it underscores the continuous evolution of healthcare costs and the need for beneficiaries to remain vigilant and proactive in managing their healthcare finances. By understanding the factors driving these adjustments, recognizing their varied impact, and implementing effective strategies, beneficiaries can better navigate the complexities of Medicare and ensure they receive the care they need without undue financial strain.
Staying informed, reviewing coverage annually, and planning proactively are the cornerstones of successful Medicare management. As 2026 approaches, these steps will be more important than ever for ensuring that your healthcare coverage remains both comprehensive and affordable.


