Maximize College Aid: Navigating 2026 FAFSA Changes for 15% More Funding
Anúncios
The landscape of college financial aid is constantly evolving, and the 2026 FAFSA Changes are set to introduce some of the most significant shifts in recent memory. For students and families planning for higher education, understanding these updates is not just beneficial, but absolutely critical to maximizing financial assistance. With the right strategies and a proactive approach, you could potentially increase your college aid by a remarkable 15% or more. This comprehensive guide will delve deep into the upcoming changes, offering actionable tips and expert insights to help you navigate the new system effectively.
Anúncios
The Free Application for Federal Student Aid (FAFSA) is the gateway to billions of dollars in federal grants, scholarships, work-study programs, and federal student loans. Its importance cannot be overstated. However, the process can often feel daunting, complex, and filled with jargon. The 2026 FAFSA Changes aim to simplify the application process for many, but they also introduce new methodologies and terminology that require careful attention. Our goal is to demystify these changes, providing you with a clear roadmap to secure the maximum possible financial aid for your college education.
From the new Student Aid Index (SAI) replacing the Expected Family Contribution (EFC) to changes in how assets and income are assessed, every aspect of the FAFSA is undergoing a transformation. Staying informed and preparing early will be your biggest advantage. Let’s embark on this journey to understand the 2026 FAFSA Changes and equip you with the knowledge to make informed decisions for your academic future.
Anúncios
Understanding the Core of the 2026 FAFSA Changes: SAI vs. EFC
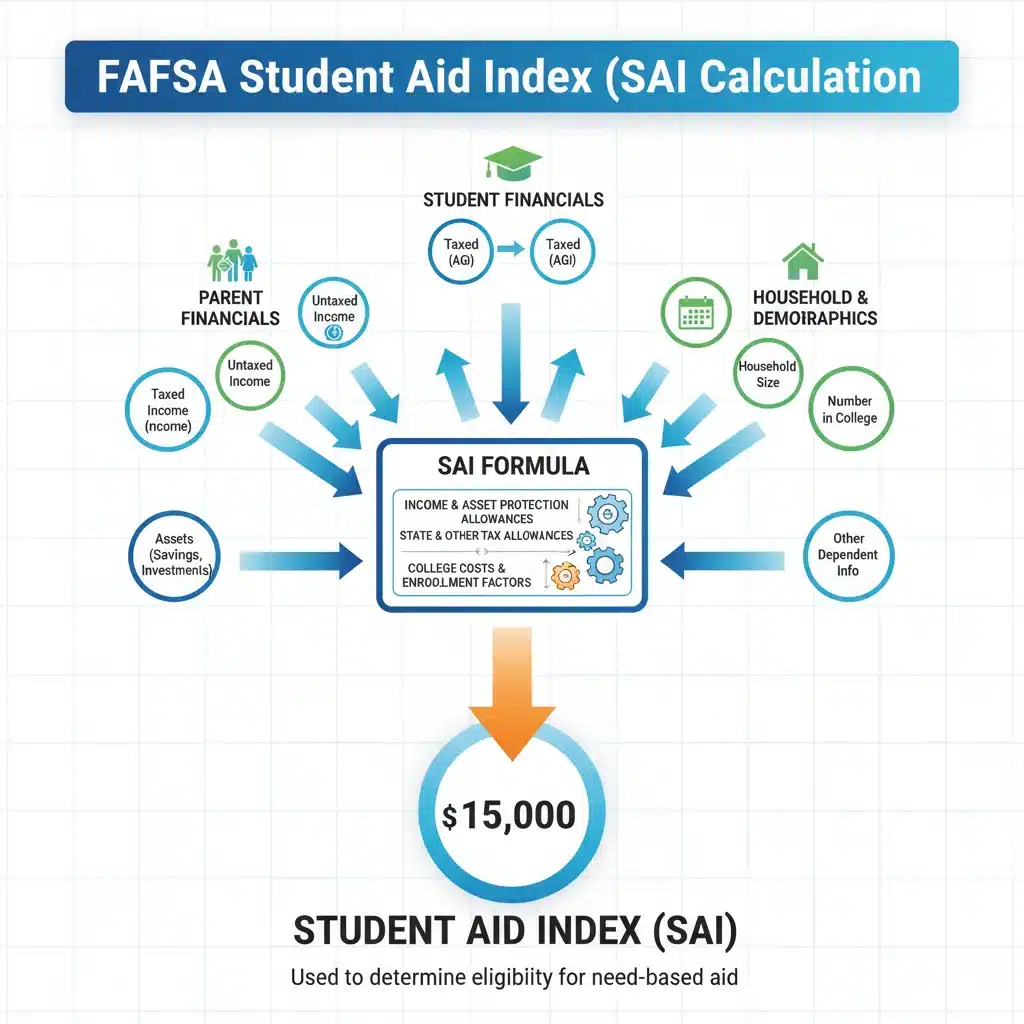
One of the most fundamental aspects of the 2026 FAFSA Changes is the replacement of the Expected Family Contribution (EFC) with the Student Aid Index (SAI). While both terms represent an eligibility index used to determine a student’s federal aid eligibility, their calculation methodologies differ significantly. Understanding this distinction is paramount to grasping how your aid package might be affected.
What was the Expected Family Contribution (EFC)?
Historically, the EFC was a number calculated by the federal government that estimated how much a family could reasonably contribute towards a student’s education costs for one academic year. It was never a direct bill, but rather an index used by financial aid offices to determine eligibility for need-based aid. A lower EFC generally meant more financial aid. The EFC calculation considered various factors, including parental income, student income, assets (excluding retirement accounts and the family home), family size, and the number of students in college.
Introducing the Student Aid Index (SAI) for 2026 FAFSA
The Student Aid Index (SAI) is designed to be a more holistic and, in many cases, more equitable measure of a student’s financial need. Unlike the EFC, the SAI can be a negative number, ranging from -1500 to a high positive number. A negative SAI indicates a higher level of financial need, potentially qualifying students for maximum Pell Grant awards and other forms of aid. This is a crucial aspect of the 2026 FAFSA Changes that could significantly benefit students from low-income backgrounds.
Key differences in the SAI calculation under the 2026 FAFSA Changes include:
- No. of Students in College: The previous system considered how many family members were simultaneously enrolled in college, often reducing the EFC for families with multiple children in higher education. The SAI calculation, however, eliminates this benefit. This is a major change that could negatively impact middle-income families with multiple college-bound children.
- Child Support: Previously, child support received was counted as untaxed income. Under the new rules, child support received will be excluded from income, which could lower a family’s SAI and increase aid eligibility.
- Small Business and Farm Assets: The previous FAFSA excluded small business and farm assets if the family owned and operated them and had 100 or fewer full-time employees. The 2026 FAFSA Changes will now include these assets in the SAI calculation, which could increase the SAI for some families.
- Federal Tax Information (FTI) Integration: The new FAFSA will rely more heavily on direct data exchange with the IRS, making the application process simpler and potentially reducing errors. This is a significant step towards streamlining the process, a key goal of the 2026 FAFSA Changes.
Understanding these shifts is the first step in strategically planning for your financial aid. The move to SAI is not just a name change; it represents a fundamental re-evaluation of how financial need is assessed, directly impacting how much aid you might receive.
Key Changes in Income and Asset Assessment for 2026 FAFSA
Beyond the EFC to SAI transition, the 2026 FAFSA Changes bring substantial modifications to how income and assets are reported and evaluated. These adjustments can significantly influence your eligibility for federal student aid. Being aware of these nuances will allow you to plan your finances effectively and optimize your aid potential.
Income Assessment Updates
The core principle remains that income is a primary determinant of financial need. However, the 2026 FAFSA Changes introduce specific alterations:
- Increased Income Protection Allowances: The new FAFSA will feature larger income protection allowances for both students and parents. This means that a greater portion of a family’s income will be shielded from the SAI calculation, potentially leading to a lower SAI and increased aid eligibility for many families. This is a positive development for those seeking to maximize their college aid under the 2026 FAFSA Changes.
- Taxable vs. Untaxed Income: While the overall categories remain, how certain untaxed income items are treated has been refined. As mentioned, child support received will no longer be considered untaxed income, which can be a substantial benefit for single-parent households.
- Direct Data Exchange with IRS: The future FAFSA will mandate the use of the IRS Direct Data Exchange (DDX), formerly known as the IRS Data Retrieval Tool (DRT). This system directly transfers tax information from the IRS to the FAFSA, simplifying the application process, reducing errors, and making it harder to manipulate income reporting. This integration is a cornerstone of the 2026 FAFSA Changes for efficiency and accuracy.
Asset Assessment Revisions
Assets play a crucial role in determining financial need, and the 2026 FAFSA Changes have several important updates in this area:
- Inclusion of Small Business and Farm Assets: This is one of the most impactful changes. Previously, if a family owned and operated a small business or farm with 100 or fewer full-time employees, the value of these assets was excluded from the EFC calculation. Under the 2026 FAFSA Changes, these assets will now be included in the SAI calculation. This could lead to a higher SAI for families who own such entities, potentially reducing their aid eligibility. Families in this situation need to plan carefully.
- Increased Asset Protection Allowances: Similar to income, asset protection allowances will also increase. This means a larger portion of a family’s non-retirement assets will be protected from the SAI calculation, which can help offset some of the other changes for certain families.
- Exclusion of Retirement Accounts and Primary Residence: It’s important to remember that qualified retirement accounts (like 401(k)s, IRAs) and the equity in a family’s primary residence continue to be excluded from the FAFSA asset calculation. This remains a consistent positive aspect for long-term financial planning.
The interplay of these income and asset changes can be complex. For instance, a family with a small business might see their SAI increase due to asset inclusion, even if their income protection allowance also rises. It’s crucial to evaluate your specific financial situation in light of these 2026 FAFSA Changes.
Strategic Planning for Maximizing Your Aid by 15% with 2026 FAFSA Changes
Achieving a 15% increase in college aid isn’t just a hopeful target; it’s an achievable goal with strategic planning and a thorough understanding of the 2026 FAFSA Changes. Here are actionable tips to help you optimize your financial aid eligibility:
1. Understand Your New SAI
The first step is to familiarize yourself with how the new SAI will be calculated for your specific financial situation. Use online SAI calculators (when they become available and are updated for the 2026 rules) to get an estimate. This will give you a baseline to work from and highlight areas where you might need to make adjustments. Pay particular attention to how the elimination of the ‘number of students in college’ benefit and the inclusion of small business/farm assets might affect your SAI.
2. Proactive Income Management
Since the FAFSA uses ‘prior-prior year’ income, the income you report on the 2026-2027 FAFSA will be from the 2024 tax year. This provides an opportunity for proactive income management:
- Delay Bonuses or Capital Gains: If possible, consider delaying the receipt of large bonuses, stock options, or capital gains until after the base year (2024 for the 2026-2027 FAFSA).
- Increase Retirement Contributions: Contributions to tax-deferred retirement accounts (401(k)s, IRAs) reduce your adjusted gross income (AGI), which is a key component of the SAI calculation. Maximizing these contributions can significantly lower your reported income for FAFSA purposes. This is a perennial strategy that remains highly effective under the 2026 FAFSA Changes.
- Consider Income Shifts for Business Owners: If you own a small business, consult with a financial advisor about strategies to manage your personal income for the base year, keeping in mind the new asset inclusion rules.
3. Strategic Asset Management
Assets are a significant factor, and managing them strategically can have a considerable impact:
- Utilize 529 Plans: Funds in a 529 college savings plan owned by a parent or dependent student are reported as a parental asset, which is assessed at a lower rate (up to 5.64%) compared to a student’s assets (up to 20%). If grandparents own the 529 plan, distributions can impact future aid, so careful planning is needed here. Under the 2026 FAFSA Changes, the treatment of 529 plans remains favorable when owned by a parent.
- Reduce Reportable Assets: If you have significant liquid assets in savings accounts or brokerage accounts, consider using them for large, one-time expenses that wouldn’t be reported on the FAFSA. Examples include paying down consumer debt (credit cards, car loans), making necessary home repairs, or purchasing a new vehicle prior to the FAFSA filing.
- Understand Small Business/Farm Asset Impact: If you own a small business or farm, this change is critical. Work with a financial planner to understand how these assets will be valued and if there are any legitimate strategies to mitigate their impact on your SAI. This might involve re-evaluating the business structure or asset allocation.
- Avoid Student-Owned Assets: If a student has significant assets in their own name, these are assessed at a much higher rate (20%) than parental assets (up to 5.64%). Consider transferring these assets to a parent-owned 529 plan or using them to pay for educational expenses before applying.
4. Early Application and Accuracy
While the 2026 FAFSA Changes aim for simplification, the importance of early and accurate application remains. Many state and institutional aid programs are first-come, first-served. Completing your FAFSA as soon as it becomes available (typically October 1st for the following academic year) is crucial. Double-check all information to avoid errors that could delay processing or lead to a less favorable aid package.
5. Understand Special Circumstances
If your family’s financial situation has changed significantly since the prior-prior year (e.g., job loss, medical expenses, divorce, death of a parent), you can appeal your financial aid award. This is known as a ‘special circumstances’ appeal. Gather documentation and contact the financial aid office at each college to explain your situation. The 2026 FAFSA Changes do not eliminate the ability to appeal, and it can be a powerful tool for families facing unforeseen financial hardship.
6. Explore Scholarships and Other Aid Sources
Federal aid is just one piece of the puzzle. Actively search for scholarships from private organizations, community groups, and the colleges themselves. Scholarships are ‘gift aid’ that doesn’t need to be repaid and can significantly supplement your federal aid package, helping you reach that 15% increase goal or even surpass it. Remember, the 2026 FAFSA Changes primarily impact federal aid, so external scholarships remains a vital avenue.
The Impact of Removing the ‘Number of Students in College’ Question
Among the various 2026 FAFSA Changes, the elimination of the question regarding the number of family members attending college simultaneously is one that could have a profound effect, particularly on middle-income families. Previously, having multiple children enrolled in higher education at the same time significantly reduced a family’s EFC, often leading to increased eligibility for need-based aid. With this question removed, the SAI calculation will no longer provide this benefit.
Who will be affected most?
- Middle to Upper-Middle Income Families: These families often qualified for more aid when they had two or more children in college due to the EFC reduction. Without this adjustment, their SAI will likely be higher, potentially reducing their eligibility for need-based federal and institutional grants.
- Families with Close-in-Age Siblings: Households where children are only a year or two apart and will overlap in college will feel this change acutely. The financial burden of multiple tuition bills will be less mitigated by federal aid.
Strategies to Mitigate the Impact:
While this change is a significant hurdle, there are ways to prepare:
- Increased Savings: If you anticipate having multiple children in college, accelerate your savings efforts into 529 plans or other tax-advantaged accounts.
- Focus on Merit Aid: Encourage students to pursue academic excellence, extracurricular involvement, and leadership roles that can lead to merit-based scholarships directly from colleges. These are not tied to financial need and are unaffected by the 2026 FAFSA Changes.
- Community College First: Consider having one or more children attend community college for the first two years to reduce overall costs, then transfer to a four-year institution. This can significantly lessen the financial strain during overlapping college years.
- Appeal Process: If your family faces genuine hardship due to this change, and the college’s financial aid offer is insufficient, don’t hesitate to use the appeal process. Explain your unique circumstances, especially the burden of multiple college tuitions.
This particular aspect of the 2026 FAFSA Changes underscores the need for comprehensive college planning that goes beyond just federal aid. Diversifying your funding strategy will be more important than ever.
The Role of the IRS Direct Data Exchange (DDX) in 2026 FAFSA
A cornerstone of the modernization efforts within the 2026 FAFSA Changes is the enhanced reliance on the IRS Direct Data Exchange (DDX). This system is designed to streamline the data collection process, improve accuracy, and reduce the burden on applicants.
How DDX Works:
Instead of manually entering tax information, applicants (and their parents, if applicable) will provide consent for the Department of Education to directly access their tax data from the IRS. This data is then securely transferred to the FAFSA form. This mandatory consent is a critical step in the application process. Without it, the FAFSA cannot be processed, and students will not be eligible for federal aid.
Benefits of DDX:
- Simplified Application: For most applicants, this means less manual data entry and a faster, more user-friendly experience.
- Reduced Errors: Direct transfer of data from the IRS minimizes the potential for human error in reporting income and tax information.
- Increased Security: The DDX is designed with robust security protocols to protect sensitive financial information.
- Improved Accuracy: By using official IRS data, the accuracy of financial aid eligibility assessments is significantly enhanced.
Potential Challenges and Considerations:
- Mandatory Consent: As mentioned, providing consent is not optional. Families who are hesitant to share their tax data will need to understand that it’s a prerequisite for federal aid.
- Timeliness of Tax Filing: Since the DDX relies on tax data, it’s more important than ever to file your taxes promptly. The 2026-2027 FAFSA will use 2024 tax information, so ensuring your 2024 taxes are filed and processed by the IRS well before you plan to submit the FAFSA is crucial.
- Non-Filers: For individuals who are not required to file taxes, the process will still involve attesting to non-filer status, but the DDX will verify this with the IRS.
The DDX is a significant technological leap for the FAFSA and a key part of the 2026 FAFSA Changes. While it aims to simplify, applicants must be prepared for the mandatory consent and ensure their tax information is up-to-date with the IRS.
Understanding Pell Grant Eligibility with the 2026 FAFSA Changes
The Pell Grant is often the foundation of a federal financial aid package, providing direct aid to students from low-income backgrounds that does not need to be repaid. The 2026 FAFSA Changes introduce a new approach to determining Pell Grant eligibility, aiming to expand access for more students.
New Pell Grant Eligibility Rules:
- Maximum Pell Grant Eligibility: Students whose SAI is -1500 (the lowest possible) will automatically qualify for the maximum Pell Grant award. This is a clear indicator of the government’s intent to prioritize aid for the neediest students.
- Direct Certification for Certain Income Levels: Students from households below a certain poverty threshold (e.g., 175% of the federal poverty level for single-parent households, 150% for two-parent households) will also be directly certified for the maximum Pell Grant. This simplifies the process for many low-income families.
- Sliding Scale for Other Students: For students whose SAI is above -1500 but still within the Pell Grant eligibility range, the award amount will be determined by a sliding scale based on their SAI and the cost of attendance at their chosen institution.
Impact of the Changes:
These 2026 FAFSA Changes are expected to:
- Increase Pell Grant Access: More students, particularly those with the greatest financial need, are anticipated to qualify for Pell Grants or receive higher amounts.
- Simplify Determination: The direct certification for maximum Pell Grants for certain income levels will make the process more straightforward for eligible families.
- Potential for More Aid: For many students, the revised Pell Grant eligibility could mean a significant increase in non-repayable aid, directly contributing to the goal of maximizing college aid by 15% or more.
It is crucial for students and families to understand the new Pell Grant rules as part of the broader 2026 FAFSA Changes, as this grant can dramatically reduce the need for loans and make college more affordable.
The Simplified FAFSA Form: What to Expect
One of the overarching goals of the 2026 FAFSA Changes is to simplify the application process. The form itself has undergone a significant redesign, aiming to make it more accessible and less intimidating for applicants.
Key Simplifications:
- Fewer Questions: The number of questions on the FAFSA form has been substantially reduced. This is a major improvement, cutting down on the time and effort required to complete the application.
- User-Friendly Interface: The online FAFSA will feature a more intuitive and mobile-friendly design, making it easier to navigate on various devices.
- Streamlined Dependency Status Questions: The questions determining a student’s dependency status have been simplified, aiming for clearer guidance.
- Improved Language: The language used throughout the form is being revised to be clearer, less technical, and more understandable for a broader audience.
What Remains Important:
- Accurate Information: While fewer questions, accuracy is still paramount. Errors can cause delays or reduce aid eligibility.
- Timely Submission: The importance of submitting the FAFSA early (as close to October 1st as possible) has not changed, especially for state and institutional aid.
- Understanding the DDX: As discussed, the mandatory consent for the IRS Direct Data Exchange is a new, crucial step that applicants must understand and complete.
The simplified FAFSA form, as part of the 2026 FAFSA Changes, aims to remove barriers to applying for financial aid, encouraging more students to seek the assistance they need for higher education.
Common Misconceptions and How to Avoid Them with 2026 FAFSA Changes
With significant reforms like the 2026 FAFSA Changes, misconceptions are bound to arise. Dispelling these myths is crucial for effective planning and ensuring you don’t miss out on potential aid.
Misconception 1: My Family Makes Too Much Money for Aid.
Reality: This is one of the most persistent myths. Many families believe they won’t qualify for any aid due to their income. However, eligibility for federal aid, especially unsubsidized loans, is not solely based on income. Furthermore, colleges use FAFSA data to determine eligibility for their own institutional aid, which can have higher income thresholds. The 2026 FAFSA Changes, with increased income protection allowances, might even expand eligibility for some middle-income families. Always apply!
Misconception 2: Applying Early Doesn’t Matter.
Reality: While federal aid deadlines are often later, many state and institutional aid programs operate on a first-come, first-served basis, with limited funds. Submitting your FAFSA as soon as it opens (October 1st) significantly increases your chances of receiving these types of aid. The 2026 FAFSA Changes do not alter the importance of early submission.
Misconception 3: Only Federal Aid is Available.
Reality: The FAFSA is primarily for federal aid, but it’s also the prerequisite for most state and institutional aid. Beyond that, a vast array of private scholarships from foundations, corporations, and community groups exist. Actively researching and applying for these can significantly boost your total aid package, independent of the 2026 FAFSA Changes.
Misconception 4: My Small Business/Farm Assets are Still Excluded.
Reality: This is a critical new change. Under the 2026 FAFSA Changes, small business and farm assets (even if family-owned and operated) will now be included in the SAI calculation. Families with these assets must account for this and plan accordingly, potentially consulting with a financial advisor.
Misconception 5: The FAFSA is Too Complicated to Complete.
Reality: While it has been complex, the 2026 FAFSA Changes aim to simplify the form, reduce the number of questions, and integrate directly with the IRS. While it still requires attention to detail, it should be a more user-friendly experience. Don’t let perceived complexity deter you from applying.
By understanding these common pitfalls, you can navigate the 2026 FAFSA Changes more effectively and ensure you are taking every step to maximize your college aid.
Conclusion: Preparing for a Brighter College Future with 2026 FAFSA Changes
The 2026 FAFSA Changes represent a significant overhaul of the federal financial aid system, designed to simplify the application process and expand eligibility for many students. While these changes bring new complexities, they also present unparalleled opportunities to maximize your college aid. By understanding the transition from EFC to SAI, the revised income and asset assessment rules, the impact of removing the ‘number of students in college’ question, and the role of the IRS Direct Data Exchange, you are well on your way to strategic planning.
Remember, achieving a 15% increase in your college aid is an ambitious but attainable goal. It requires proactive engagement, meticulous attention to detail, and a willingness to adapt to the new regulations. Start early, gather your financial documents, leverage the new simplified form, and don’t hesitate to seek guidance from financial aid professionals or college counselors. Your commitment to understanding and navigating the 2026 FAFSA Changes will directly translate into a more affordable and accessible higher education experience.
The path to college funding can seem daunting, but with this guide, you are now equipped with the essential knowledge and strategies to confidently approach the new FAFSA landscape. Embrace these changes as an opportunity to secure the financial future of your educational aspirations. Good luck, and here’s to unlocking maximum college aid!


